A recent national survey found 60% of Americans would rather co-buy half a home now than keep renting until solo ownership feels possible.
Cost drove interest most: 94% named at least one affordability reason, led by sharing monthly mortgage payments, splitting down payments, or reaching better homes.
Family was the most common path, with 68% open to buying with relatives, while younger and lower-income Americans showed greater openness to friends.
Nearly all prospective co-buyers wanted written agreements covering exit and payment terms, and brokers can add value as non-traditional down payment sources reached 29%.
The shift looked deeper than financing: 61% viewed co-buying with friends or family as serious as marriage, and half saw it helping avoid later-life solitude.
-
60% Prefer Co-Buying to Waiting Alone
-
Happy Halloween
Halloween falls on October 31 because the ancient Gaelic festival of Samhain, considered the earliest known root of Halloween, occurred on this day.
In the eighth century, Pope Gregory III designated November 1 as a time to praise all saints.
Soon, All Saints' Day incorporated some traditions of Samhain and the evening before was known as All Hallows Eve, and later Halloween.
Over time, Halloween evolved into a day of activities like trick-or-treating, carving jack-o-lanterns, festive gatherings, donning costumes and eating treats.
Today’s the day to eat candies and sweets to your heart’s content! Happy Halloween! -
AD Mortgage Study Finds Buying Now Beats Waiting in 61% of Historical Scenarios
Over the past 22 years, a comprehensive study found that buying a home right away led to lower total costs in 61% of historical scenarios. What stands out to me is that these benefits weren’t just about timing the market or chasing the lowest rates—instead, they depended on factors like local prices, your ability to save, and unique market conditions. As someone who’s guided families through home financing decisions for two decades, I know there’s rarely a perfect moment, but understanding your personal goals and local realities often matters more than waiting for the 'ideal' rate. My approach is always built around your long-term needs—not just the numbers—so you can move forward with confidence, no matter what the market headlines say.
Continue to full article -
How to Choose a Mortgage Lender (2026)
Over the past two decades guiding clients across California, I’ve learned that choosing the right mortgage lender is about far more than chasing the lowest rate. Start by requesting written Loan Estimates from several lenders—this gives you a side-by-side look at rates, fees, and all terms. Pay attention to the lender’s type and the loan options they offer (think fixed vs. adjustable rates), but also look closely at how clearly they explain things, how reliably they communicate, and how they manage their closing timelines. In my practice, I place a premium on clarity and trust, taking time to match clients with a loan that truly fits their future—not just their present. Whether you’re a first-time buyer, refinancing, or exploring specialized programs, the right lender will always prioritize your needs and keep the process transparent from start to finish.
Continue to full article -
مقرونبهصرفه بودن، انتخاب هوشمندانه را ممکن میکند
خریداران خانه اول اغلب به دلیل محدودیت بودجه، از برخی خواستههای خود چشمپوشی میکنند؛ بهطوریکه ۵۸٪ آنها بودجه را دلیل اصلی مصالحهها میدانند. درک و پذیرش محدودیتهای مالی از همان ابتدا، با دریافت پیشتاییدیه و تحقیق بازار، به خریداران کمک میکند تا با برنامهریزی، خودشان درباره اولویتها و مصالحهها تصمیم بگیرند. تعیین اولویتها و مشخص کردن موارد قابل چشمپوشی پیش از شروع جستجو، از تصمیمگیریهای احساسی جلوگیری کرده و باعث میشود مصالحهها کمتر به چشم باختن بیایند.
Continue to full article -
FHA Loans Can Help Buyers Buy Sooner
FHA loans can be a powerful tool for buyers hoping to move into their own home sooner, especially when saving for a large down payment feels out of reach. With as little as 3.5% down for those with credit scores of 580 and above—and even options for buyers starting at 500—these programs offer a path forward for many families. Flexible qualifying standards, the ability to use gift funds, and often lower interest rates than conventional loans help open doors that might otherwise feel closed.
That being said, eligibility is key: lenders typically prefer a 43% debt-to-income ratio, stable two-year income history, and owner occupancy. It’s also important to plan ahead for costs beyond your down payment, including typical closing costs of 2%-6%, a 1.75% upfront mortgage insurance premium, and annual insurance thereafter.
There are tradeoffs to be mindful of: FHA loans are for primary residences, have specific appraisal and property standards, and come with lower loan limits. Buyers may encounter stiffer competition from cash offers, but the opportunity to build equity sooner is real. For clients with limited savings or less-than-perfect credit, FHA loans often make sense—just remember to shop multiple approved lenders, compare all the fees, and consider refinance options down the line.
With over 20 years guiding families through decisions like these, I always strive to match each client with the right loan for their unique situation. My approach is to understand your bigger picture, offer honest advice, and help you move forward with confidence—whether that means choosing FHA, conventional, or another path entirely.
-
Start With a Plan, Not a Listing
Over my two decades guiding families through the homebuying journey, I’ve learned that a thoughtful plan always comes before the search for listings. Before falling in love with homes online, it’s essential to get clear on your income, debts, monthly bills, and—most importantly—what you’ll be truly comfortable paying each month. Homeownership should feel empowering, not like a monthly squeeze.
I always encourage clients to check their credit early, address any report errors, and pay down balances where possible. Even modest improvements here can put you in a stronger position for better loan terms, saving real money over time.
It’s not just about the down payment, either—closing costs, moving expenses, and those first repairs can add up quickly. Planning for these from the outset helps keep the experience positive and free from unwelcome surprises.
Pre-approval isn’t just a box to check—it sharpens your home search, demonstrates your seriousness to sellers, and can give you a valuable edge if you end up in a competitive offer situation.
Finally, surround yourself with a great team. I work closely with buyer’s agents who know our local CA markets inside and out, spot red flags, and negotiate with clarity and care. Take your time through every step—look beyond the staging, focus on the fundamentals, and stay steady all the way to closing.
My approach is always built on trust, honest guidance, and a deep commitment to your long-term financial health—because a mortgage should fit your life, not the other way around.
-
Mortgage Rates Are Above 7%, So Why Are Experts Saying Now Could Be a Good Time to Buy?
With mortgage rates now sitting above 7%, many buyers feel understandably cautious. But as someone who’s guided families through every kind of market over the past two decades, I can tell you: opportunity often shows up in unexpected ways. Right now, we’re seeing more homes for sale, and about 21% of sellers are making price cuts or offering concessions. That’s real negotiating room for buyers who know where to look—and how to approach their options. Every local market is different, so exploring neighborhoods and understanding the landscape is crucial. My focus has always been finding the right fit for your unique situation, not just chasing rates. If you’re weighing your choices, remember that today’s market is more than just numbers—it’s about timing, strategy, and knowing what’s possible for you.
Continue to full article -
Mortgage Pre-Approval, Explained: Your First Step to Buying in Laguna Woods
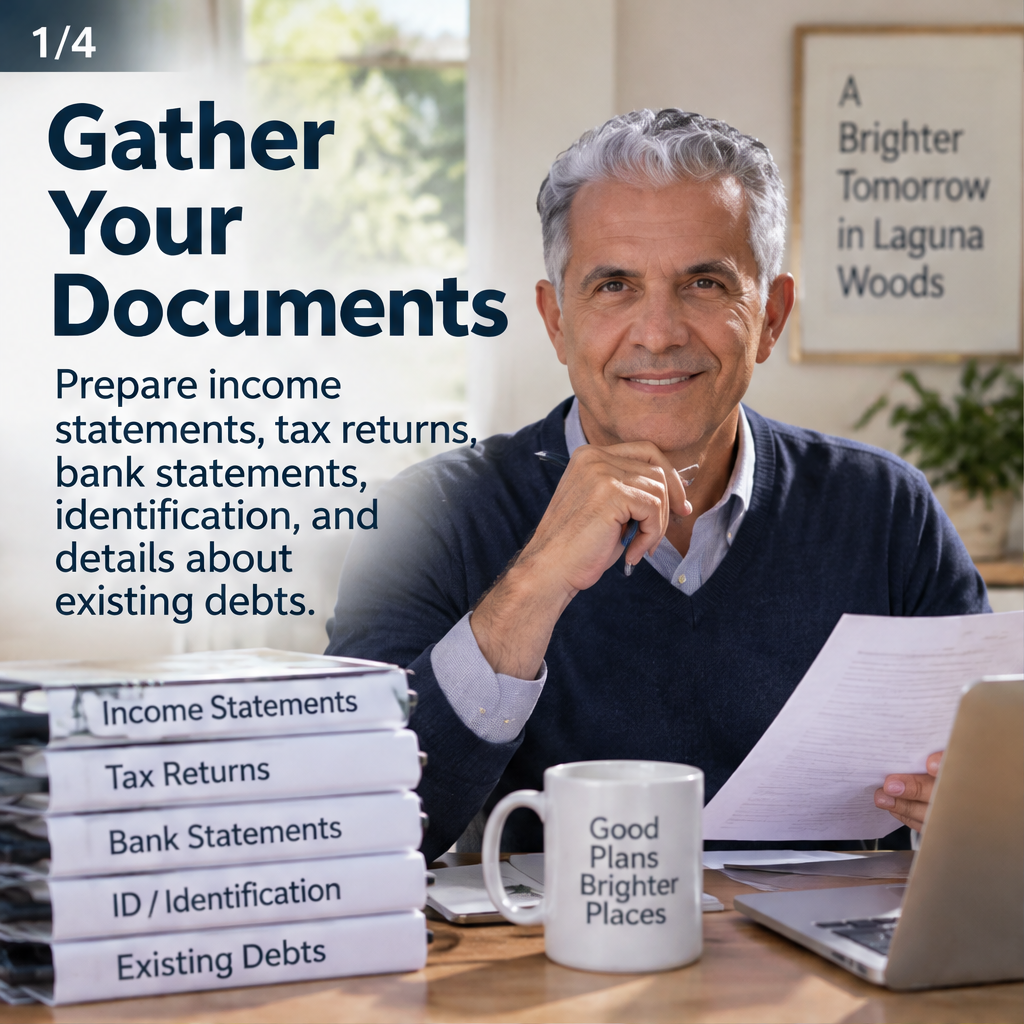
Gather Your Documents: Prepare income statements, tax returns, bank statements, identification, and details about existing debts.
Review Your Finances: A lender evaluates your income, credit, assets, and debt to estimate a comfortable borrowing range.
Get Your Letter: Once reviewed, your pre-approval letter shows sellers you are a serious buyer—but it is not final loan approval.
Ready to shop in Laguna Woods? Connect with a mortgage broker to review your options, strengthen your application, and take the next step with confidence.Continue to full article -
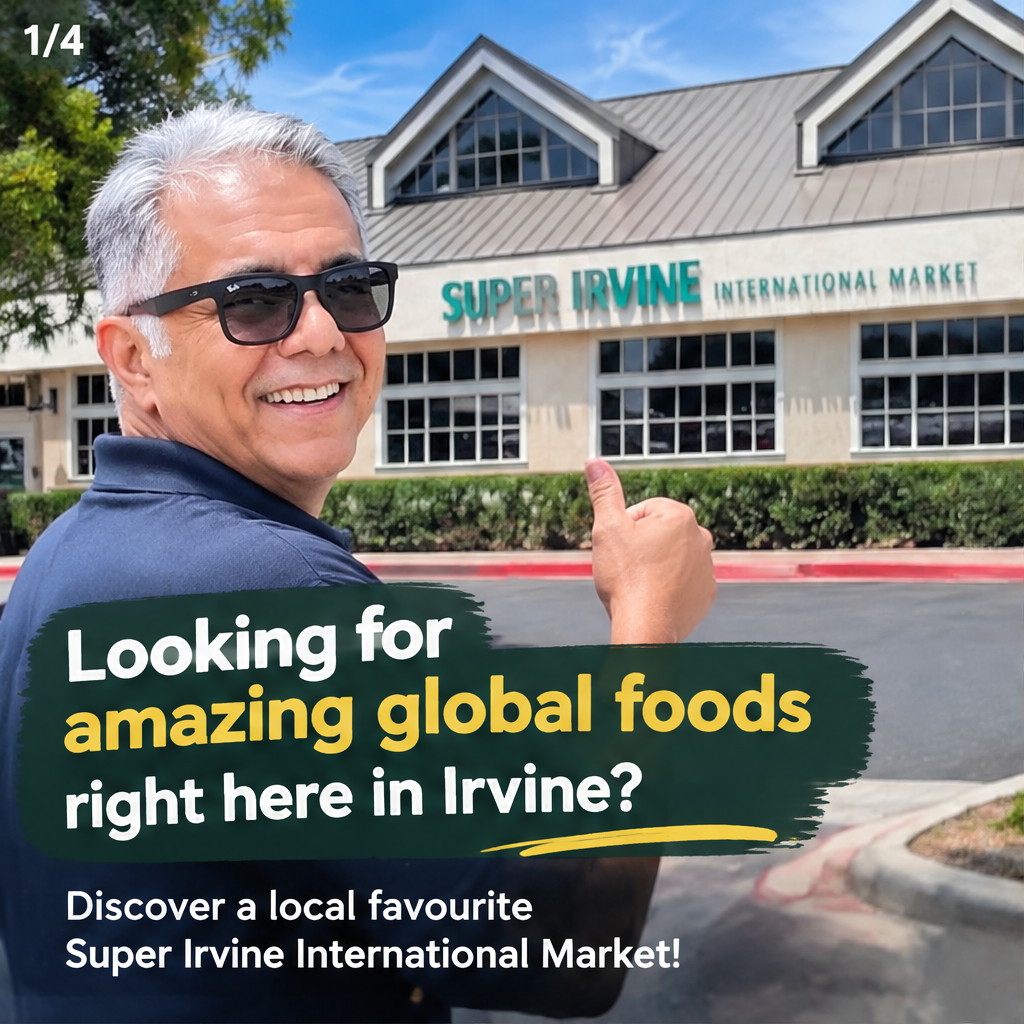
Super Irvine international market
Global Flavors—Explore international aisles filled with specialty ingredients, snacks, sauces, and pantry staples for meals from around the world.
Local Favorite—At 5331 University Dr, Super Irvine helps neighbors find familiar favorites and discover something new in one convenient stop.
Shop With Purpose—Build a flavorful grocery run, try a new ingredient, and support a neighborhood market serving Irvine’s diverse community.
Plan Your Visit—Save this spotlight, share it with a foodie friend, and visit Super Irvine at 5331 University Dr, Irvine, CA 92612.Continue to full article